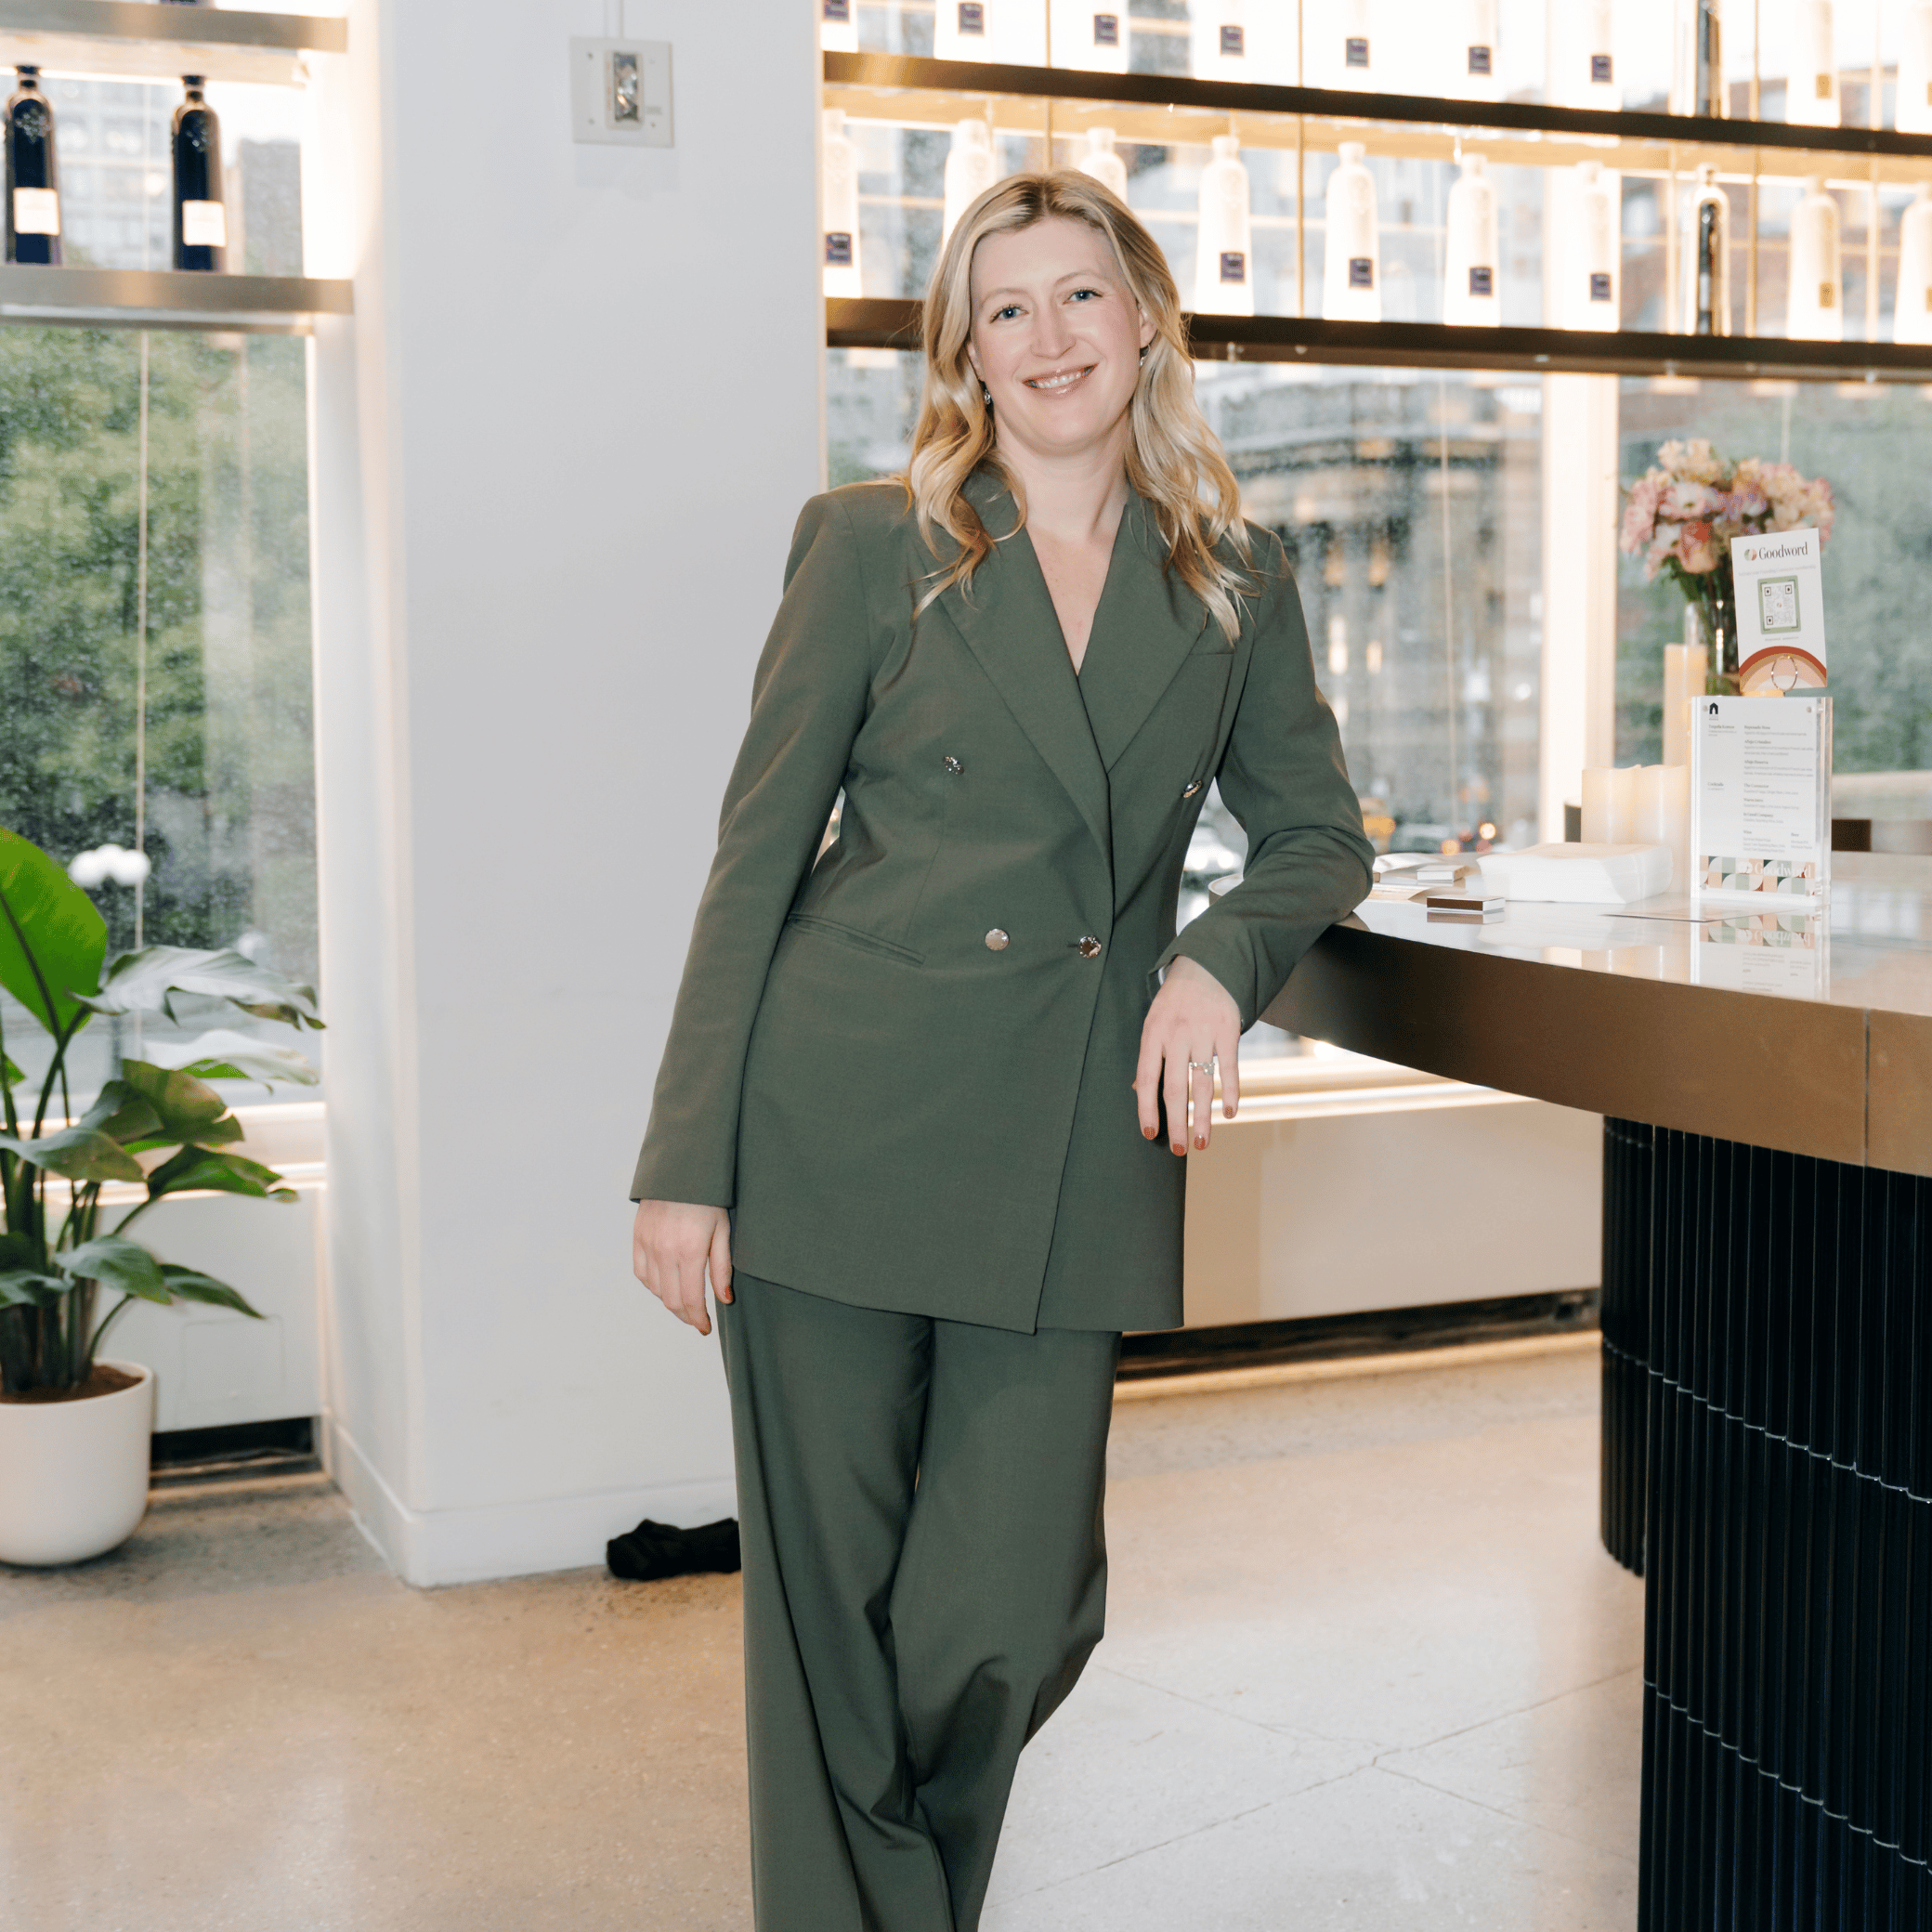
Most fundraising advice tells founders not to take investor rejection personally. Caroline Dell's account of raising Goodword's first round is more useful than that, because she opens by admitting the advice doesn't work.
"It ultimately felt like, did this person believe in me, Caroline, as a professional, as a leader, as a founder? And so those no's were hard."
Our co-founder and CEO said that on The Kara Goldin Show, and it's the part of fundraising that rarely survives into the playbooks. Investor rejection isn't experienced as a portfolio decision. It's experienced as a verdict. Telling founders otherwise doesn't make them more resilient. It just adds failing at resilience to the list of things they're apparently failing at.
The full conversation is on The Kara Goldin Show, and a lot of it is about what happens in the gaps between the no's. Here's what we took from it.
The standard reframe is that fundraising is a numbers game. That's true, and on its own it does nothing. Knowing that a fund passes on almost everything it sees is no help at six in the evening on the day one of them passed on you.
What helps is a number that comes with an instruction attached. Caroline's version:
"You're actually probably going to get 98% wrong. But you only need 2% right."
That isn't a softer way of saying don't take it personally. It's a statement about how many conversations have to be in flight for the arithmetic to work at all. If 98 percent is the expected result rather than a bad one, a single no carries almost no information, and a run of them tells you only that you haven't reached the 2 percent yet.
The line Caroline returns to is the one that does the real work:
"Pipeline cures all. There's lots of investors to talk to. Don't stop after 10, 20, even 50 conversations."
This matters more than any mindset trick, because investor rejection does its damage in two places and founders only notice one of them. The no itself costs you one investor. What it usually costs you on top of that is the week you spend rewriting the deck instead of booking meetings. Pipeline is the thing that decays while you sit with the last conversation, and it's the one variable entirely within your control.
There's a blunt test in there. If a no leaves you with fewer conversations booked than you had that morning, the no won. If it doesn't, it was a data point.
Building that pipeline in the first place is a separate discipline with its own mechanics, and we have written about those in the investor flywheel.
Caroline has been on the other side of a decision like this. At Chief, an initiative she was running was pulled, and she described how quickly the framing moved:
"We went from conversations with the board that were like, how fast can you launch this, Caroline, to, I think we need to postpone it indefinitely to put the business resources in other places."
Nothing about the work changed between those two conversations. The resourcing picture did. Investors make that same call constantly and almost never explain it, because the true reason tends to be internal: a thesis shift, a competing deal in the same slot, a partner leaving, a portfolio company that suddenly needs a bridge. None of that is visible from the outside, and very little of it is about the founder in the room.
Knowing this doesn't make a no land any softer on the day. It does mean the information content of any single one is close to zero, and that reading a stack of them as a referendum on the company is a category error.
None of this means every investor rejection is noise. Some of them carry real information, and the tell is repetition rather than intensity. One investor who thinks the market is too small is expressing a view. Five who independently land on the same doubt, without being walked into it by the same slide, are describing something true about how the business reads from the outside.
The useful filter is whether the objection survives being asked about. Push once, politely. If the answer gets more specific, there's something there worth fixing. If it gets vaguer and warmer, the decision was made on other grounds and the reason you were given was a courtesy. Founders lose weeks rebuilding a deck around the courtesy.
Goodword's round did not close along a tidy curve. It went quiet over the holidays, which is the stretch that persuades a lot of founders their round has died. It hadn't. The team came back on 5 January and the round was oversubscribed inside thirty days.
Caroline's read on that is deliberately unglamorous. Sometimes you keep going. That sounds like a platitude until you notice what it rules out, which is treating a slow December as a verdict on the business.
The distinction worth holding is between persisting on the pipeline and persisting on the pitch. Keep the conversations coming regardless. Change the deck when several investors independently trip on the same slide, not because one did.
The counterweight to a stack of no's is that the yeses you need are few, and they tend to arrive from somewhere unglamorous. Goodword's first engineer never saw a job posting.
"I never posted a job description, but you know, within days, I was on the phone with Patrick, and we had a plan to chat and to explore. And he joined me 10 hours a week."
The offer was not a competitive package, and Caroline didn't pretend it was.
"I took my very very first friends and family check from my dad, and I said I could pay you 100 bucks an hour for 10 hours a week, that's all I've got."
Ten hours a week and total honesty about the constraint. That is what a yes looked like at the point when the no's still heavily outnumbered it.
It's also worth noticing where that yes came from. The people who back you before there's much to back are usually people who already knew something about you, which is the argument behind luck is something you build.
Read the email once. Look for the single line that says something specific about fit, and disregard the rest, which is written to be kind and unfalsifiable in roughly equal measure. Put the fund on a list to revisit in eighteen months, because a no now is frequently a not yet.
Then book something. Not as a coping mechanism. Because pipeline is the only thing an investor rejection can genuinely damage, and that damage comes from a calendar going quiet, not from the email itself.
Investor rejection is going to feel personal, and Caroline's point isn't that it shouldn't. It's that feeling it and letting it thin your pipeline are separate events, and only the second one costs you the round.
And if the wider idea lands, that the people around you are the asset almost nobody has a system for, that's the problem we built Goodword to solve.